Smithfield Depot Branch Review: July 2025 to September 2026
Prepared for the Managing Director, Wattle Lane Distributors. All dollar amounts are net sales or discounts in AUD, treated as ex GST (the source does not label GST).
Executive Summary
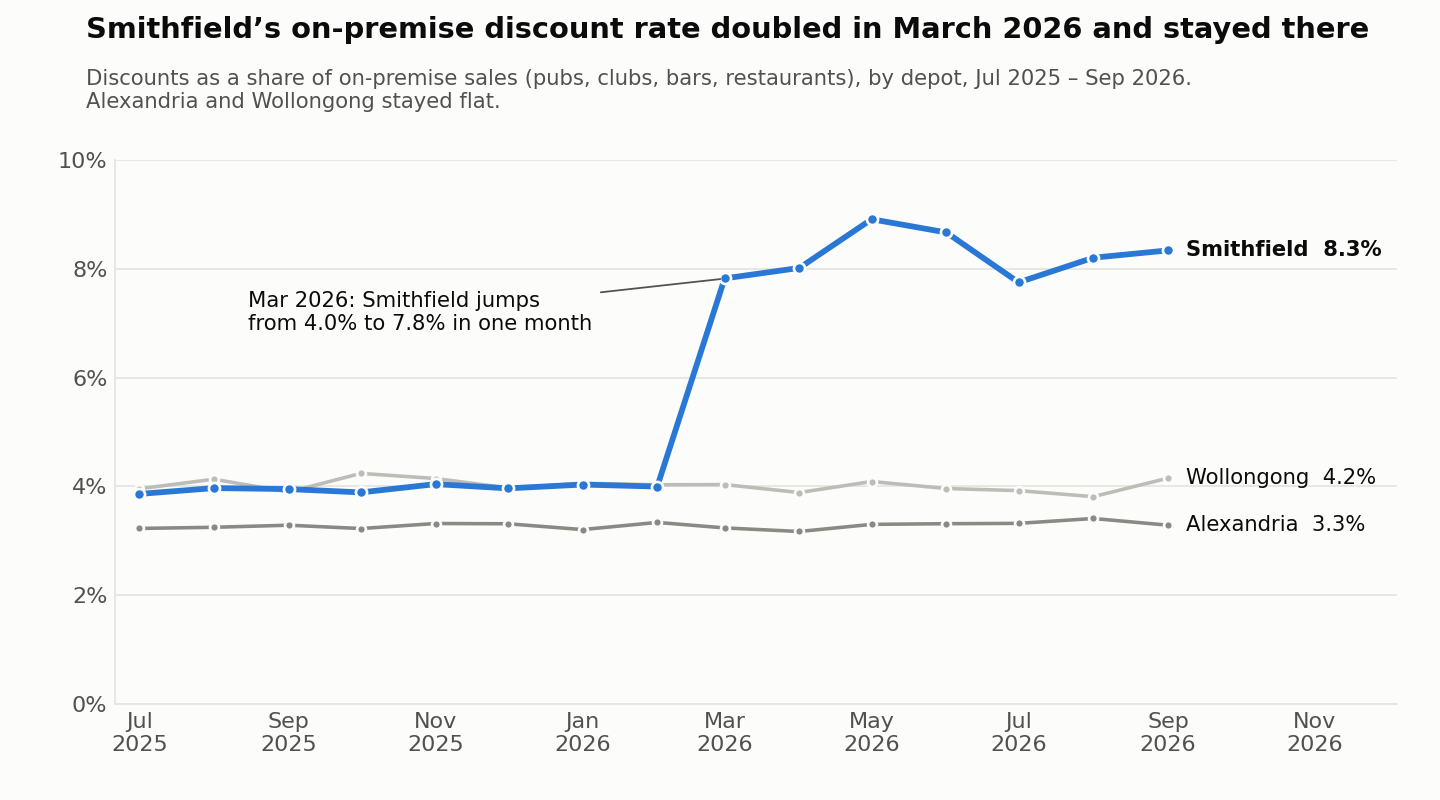
- Smithfield's on-premise discounts doubled in March 2026 and cost about $47,600 more than the old terms in March to September 2026. The on-premise discount rate (pubs, clubs, bars and restaurants) went from 4.0% (July 2025 to February 2026) to 8.2% (March to September 2026). Alexandria stayed at about 3.3% and Wollongong at about 4.0%. The whole jump sits with 13 Western Sydney pubs and clubs. If the pattern continues it is worth about $81,700 a year.
- Smithfield's sales growth is not turning into profit. July to September 2026 sales were up 7.1% on the same quarter last year, but gross margin fell from 25.5% to 24.5% and invoices barely moved (1,765 to 1,776). Alexandria and Wollongong lifted their margins over the same period. Had Smithfield held last year's margin, it would have earned about $20,500 more gross profit in the quarter.
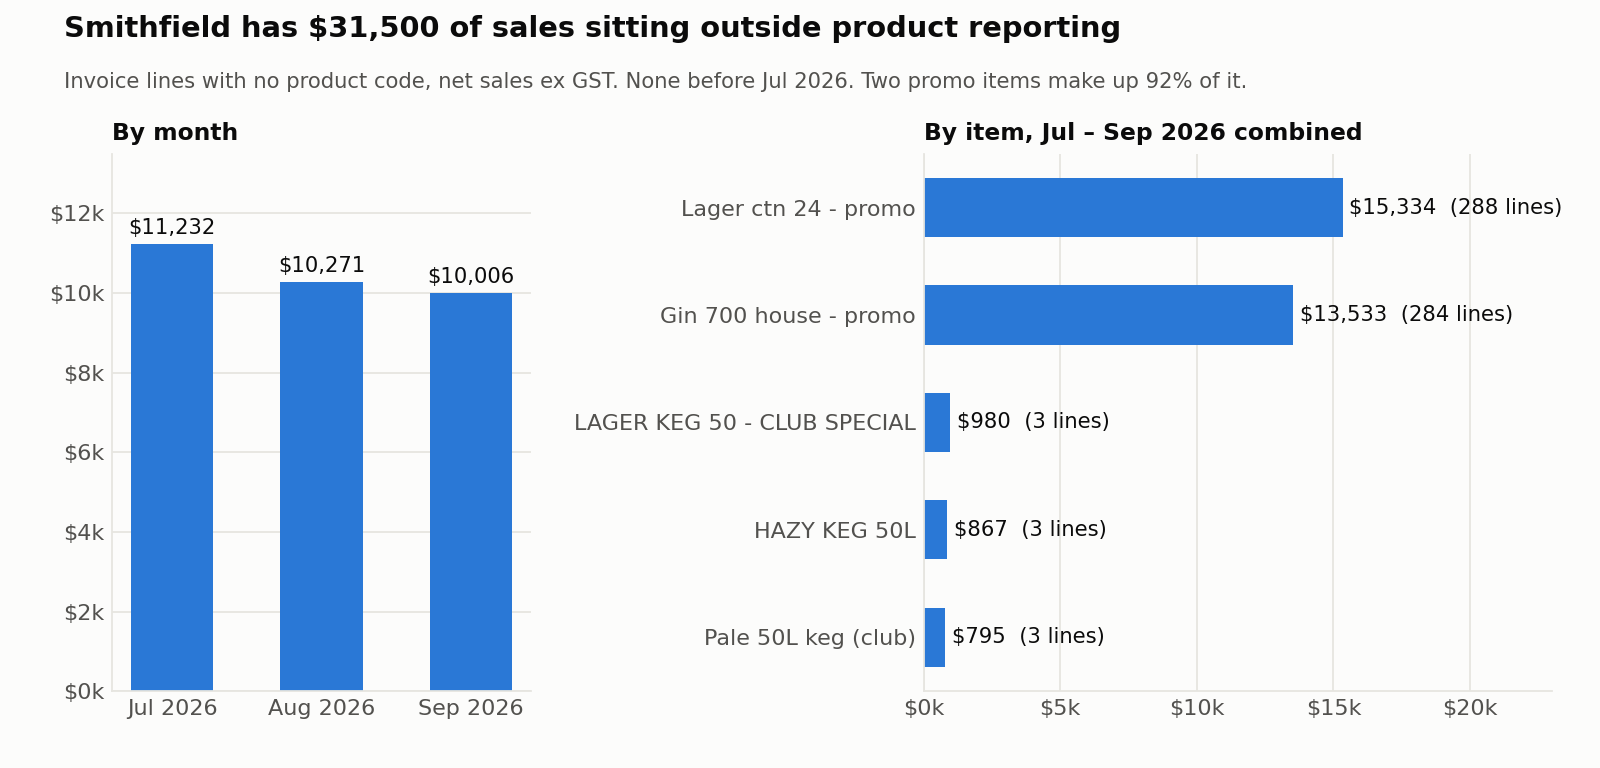
- $31,500 of Smithfield sales are invisible to product reporting. From July 2026, 581 invoice lines for promo lager, promo gin and club kegs were invoiced without product codes. That is 98.7% of the company's total of such sales, so the depot cannot check margin, stock or supplier promo claims on them.
- Receivables are in decent shape, but two dead grocer accounts hold $9,458. That is 91.7% of Smithfield's debt more than 60 days overdue ($10,313). Smithfield holds 13.7% of the company's 60+ day debt, against 77.2% at Wollongong.
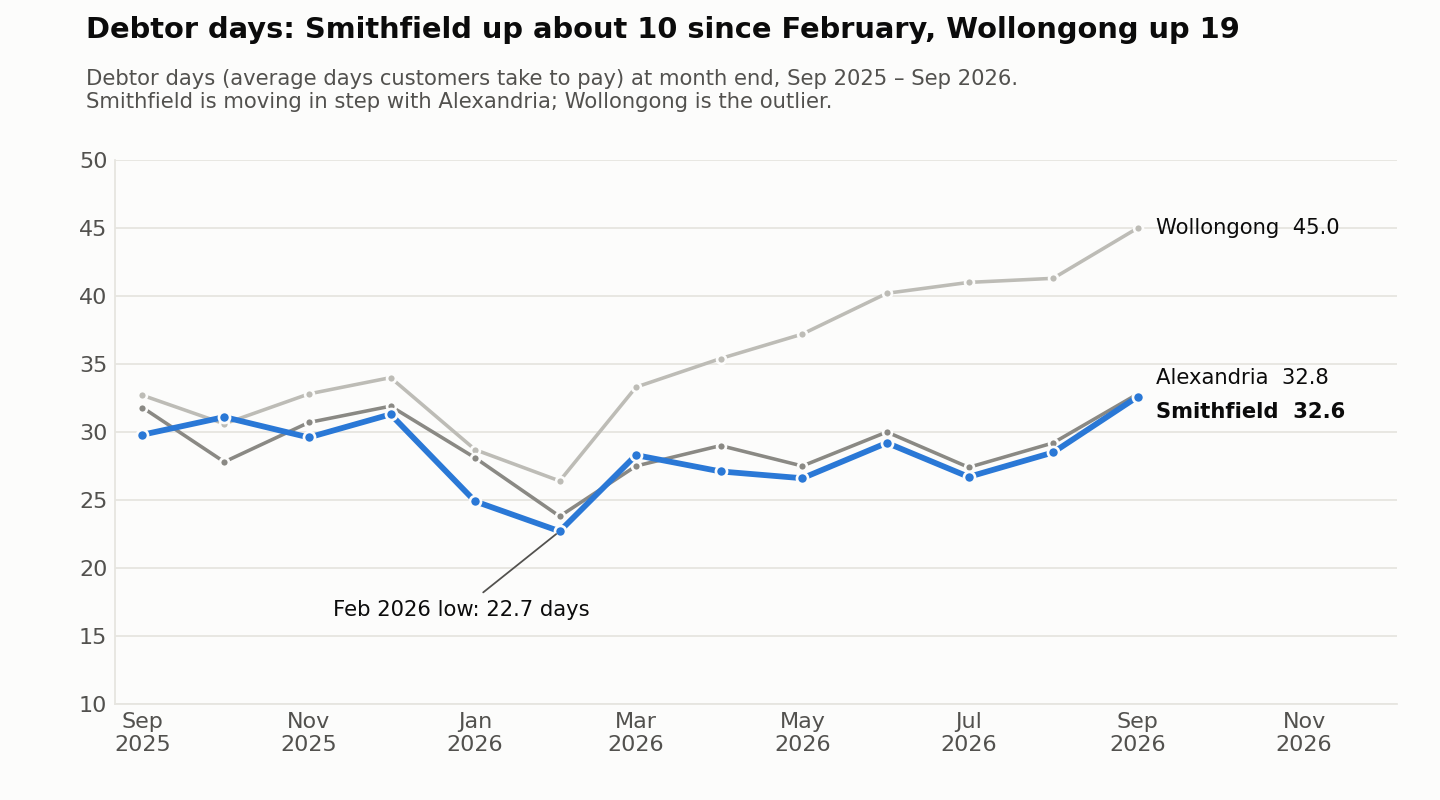
- Debtor days drifted up about 10 days since February (22.7 to 32.6 in September 2026), in step with Alexandria. Wollongong is much worse at 45.0.
Finding 1: Western Sydney on-premise discounts doubled from March 2026
What we found
Smithfield's on-premise discount rate averaged 4.0% from July 2025 to February 2026, with every month between 3.9% and 4.0%. In March 2026 it jumped to 7.8%, peaked at 8.9% in May 2026 and was 8.3% in September 2026. Over March to September 2026 it averaged 8.2%. Nothing like this happened elsewhere:
| Depot | On-premise discount rate, Jul 2025 – Feb 2026 | Mar – Sep 2026 |
|---|---|---|
| Alexandria | 3.3% | 3.3% |
| Smithfield | 4.0% | 8.2% |
| Wollongong | 4.1% | 4.0% |
 Open full-size chart ↗
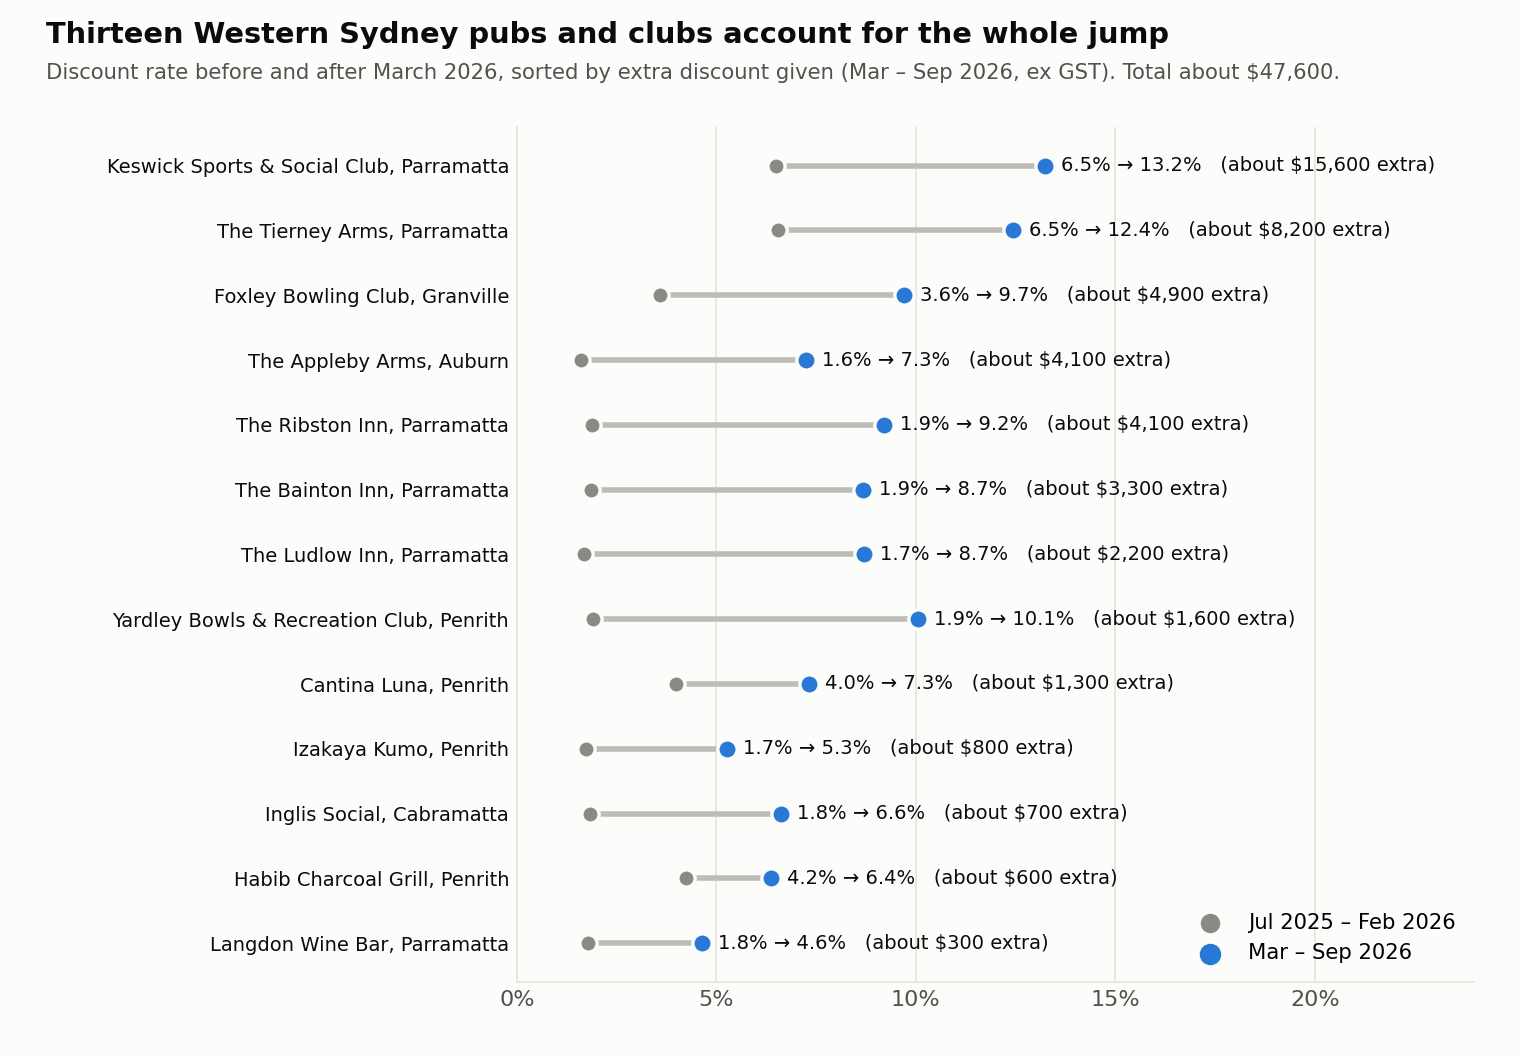
The jump is concentrated. Of Smithfield's 24 on-premise customers, 13 had their rate rise by more than 2 percentage points. All 13 are in the Western Sydney territory (Parramatta, Penrith, Granville, Auburn and Cabramatta). The South West and Hills customers did not move: for example Garrity's Hotel, Liverpool went from 3.8% to 3.5%.
 Open full-size chart ↗
To size the cost, we asked what each customer's March to September discounts would have been at their own July 2025 to February 2026 rate. The difference is the "extra discount":
| Depot | Customers with a rate in both periods | Extra discount, Mar – Sep 2026 |
|---|---|---|
| Alexandria | 47 | −$700 (no increase) |
| Smithfield | 19 | $48,100 |
| Wollongong | 26 | −$900 (no increase) |
For the 13 Western Sydney customers the extra discount is $47,600 out of $82,100 in total discounts they received. That is about $6,800 a month, or about $81,700 a year if the March to September pattern continues. The biggest amounts:
| Customer | Rate before | Rate after | Extra discount Mar – Sep 2026 |
|---|---|---|---|
| Keswick Sports & Social Club, Parramatta | 6.5% | 13.2% | $15,600 |
| The Tierney Arms, Parramatta | 6.5% | 12.4% | $8,200 |
| Foxley Bowling Club, Granville | 3.6% | 9.7% | $4,900 |
| The Appleby Arms, Auburn | 1.6% | 7.3% | $4,100 |
| The Ribston Inn, Parramatta | 1.9% | 9.2% | $4,100 |
The top three (Keswick, Tierney Arms, Foxley) received 67.7% of the 13 customers' discounts and account for $28,700 (60.2%) of the extra discount. The sharpest rate jumps were Yardley Bowls & Recreation Club, Penrith (1.9% to 10.1%) and The Ribston Inn, Parramatta (1.9% to 9.2%).
It did not buy volume, and margin fell
- Active customers averaged 129 a month before and 127 after.
- July to September invoices: 1,765 in 2025 against 1,776 in 2026.
- Smithfield's overall gross margin (all channels) fell from 25.3% (July 2025 to February 2026) to 24.5% (March to September 2026), down 0.7 percentage points. Alexandria rose from 27.0% to 27.3% and Wollongong from 26.2% to 26.6%.
- As an independent check, that margin fall on March to September sales of $4.45 million is about $32,800 of gross profit. This overlaps with the $47,600 above, so the two should not be added together.
- Year on year (July to September), net sales grew 7.1% at Smithfield, 6.2% at Alexandria and 1.5% at Wollongong. Smithfield's margin fell from 25.5% to 24.5%, while Alexandria went from 27.1% to 27.5% and Wollongong from 26.5% to 26.8%.
- Even before March, Smithfield's margin sat about 1.7 points below Alexandria's. That gap has now widened to 2.7 points.
What I would do this month
- Pull the discount approvals and price files for the 13 named accounts. Find out who approved the March 2026 terms and whether they were promotions that were meant to end.
- Return any terms without a written agreement to each customer's old rate. Start with Keswick, The Tierney Arms and Foxley Bowling Club. Expected effect: up to about $4,100 a month from these three, and up to about $6,800 a month across all 13, if fully reversed.
- Cap on-premise discounts at about 4% (the Alexandria and Wollongong level), with branch manager sign-off needed to go above it.
- Report on-premise discount rate by territory every month so a step like March 2026 is caught in weeks, not months.
Finding 2: Promo and club-keg sales missing from product reporting
What we found
From July 2026, Smithfield recorded sales on invoice lines that are not linked to a product code ("sales outside product reporting"):
| Month | Smithfield |
|---|---|
| July 2026 | $11,232 |
| August 2026 | $10,271 |
| September 2026 | $10,006 |
| Total | $31,509 |
That is 98.7% of the company's $31,919 (Wollongong had $410 in August 2026; Alexandria had none), and 1.6% of Smithfield's July to September 2026 sales. There was nothing before July 2026.
 Open full-size chart ↗
Of the 581 Smithfield lines, 572 are two promo items: "Lager ctn 24 - promo" (288 lines, 374 units, $15,334) and "Gin 700 house - promo" (284 lines, 347 units, $13,533). The other nine lines are club kegs ("LAGER KEG 50 - CLUB SPECIAL", "HAZY KEG 50L" and "Pale 50L keg (club)"), $2,642 together.
Why it matters
Without a product code the cost of these lines is unknown. We cannot measure their margin, check stock against sales, or support a claim to suppliers for promo funding. The "promo" and "club special" names fit with the discount push in Finding 1, but the data does not prove a link; it is worth checking.
What I would do this month
- Map the five descriptions to proper product codes this week.
- Stop invoicing items that are not set up in the product list.
- Confirm promo pricing against supplier promo funding before claiming anything.
- Re-run Smithfield's July to September 2026 margin once the lines are mapped. Expected effect: October 2026 unmapped sales at $0.
Finding 3: Receivables are clean, apart from two dead grocer accounts
What we found
At 30 September 2026 Smithfield had the lowest total overdue balance of the three depots, but its 60+ day debt is mostly two accounts.
| Depot | Total overdue | Overdue more than 60 days | Share of company 60+ day debt |
|---|---|---|---|
| Alexandria | $275,037 | $6,866 | 9.1% |
| Smithfield | $218,883 | $10,313 | 13.7% |
| Wollongong | $293,704 | $58,241 | 77.2% |
Smithfield's 60+ day debt is 4.7% of what it has overdue, compared with 2.5% at Alexandria and 19.8% at Wollongong. Alexandria's 60+ day debt is lower in dollars; Wollongong's is the real problem.
Within Smithfield, two independent grocers make up 91.7%:
| Customer | Status | Overdue 60+ days | Oldest invoice (days overdue) |
|---|---|---|---|
| Ashdown Village Grocer, Penrith | Inactive | $4,843 | 94 |
| Dawkins Family Grocer, Castle Hill | On hold – COD | $4,615 | 117 |
| Hadley Fine Wines, Bankstown | Active | $713 | 102 |
| Truong's Liquor, Baulkham Hills | Active | $142 | 91 |
Debtor days (how long customers take to pay) fell to 22.7 in February 2026, then climbed to 32.6 in September 2026, a rise of 9.9 days. September 2025 was 29.8. Alexandria rose 9.0 days over the same months (to 32.8) and Wollongong 18.6 days (to 45.0).
 Open full-size chart ↗
What I would do this month
- Send Ashdown Village Grocer and Dawkins Family Grocer to formal recovery or a payment plan now, and decide on a provision for about $9,500.
- Ask Hadley Fine Wines for the $713 that is over 60 days. Its total owing is $8,446, so it is worth a call.
- Find out why debtor days rose about 10 days since February, before it becomes a trend. Part of it may be seasonal: Alexandria moved the same way.
Watchlist
- Debtor days: Smithfield 22.7 (February 2026) to 32.6 (September 2026). Check whether October stays above 30.
- Western Sydney discounts: after the actions above, the on-premise rate should fall back towards 4.0% (September 2026: 8.3%).
- Unmapped lines: should reach $0 in October 2026.
- Credit notes: company-wide credits total $363,352, including $17,521 of pricing-adjustment credits (such as promo prices not applied). The data has no depot split, so we cannot judge Smithfield's share. Ask for one.
- Small orders: Smithfield charges a delivery fee on 93.0% of orders under $250 (14.5% of invoices), in line with Alexandria (92.3%) and far better than Wollongong (45.9%). Keep it there; 88 small orders went without a fee.
- Wollongong (outside this depot's control): debtor days at 45.0 and $58,241 of 60+ day debt are the biggest receivables risk in the company.
About the data
- Source: 13 Branch Control extracts, all complete. Trading data covers July 2025 to September 2026; debtor days cover September 2025 to September 2026; receivables are as at 30 September 2026.
- "Before" is July 2025 to February 2026 (8 months); "after" is March to September 2026 (7 months).
- The source does not label GST. Figures are treated as ex GST.
- Credit notes have no depot column, so they are not attributed to Smithfield.
- Margin on unmapped lines cannot be measured, and it is not known whether depot margin includes them.
- The extra-discount method compares each customer's after-rate with their own before-rate, so it does not depend on how the discount rate is defined. Five Smithfield on-premise customers have no discounts in one period and are left out. The $81,700 a year is a simple projection, not a forecast.